Start with the financial need, then compare the contracts
Life insurance is a promise to pay a stated benefit when an insured person dies while a policy is in force. The Washington Office of the Insurance Commissioner’s life-insurance guidance explains the contract and its coverage types. Begin your comparison with the people who depend on your income, debts and final expenses, education needs, and the protection you already have. A neat “term always wins” rule skips the question of how long your family needs the death benefit.
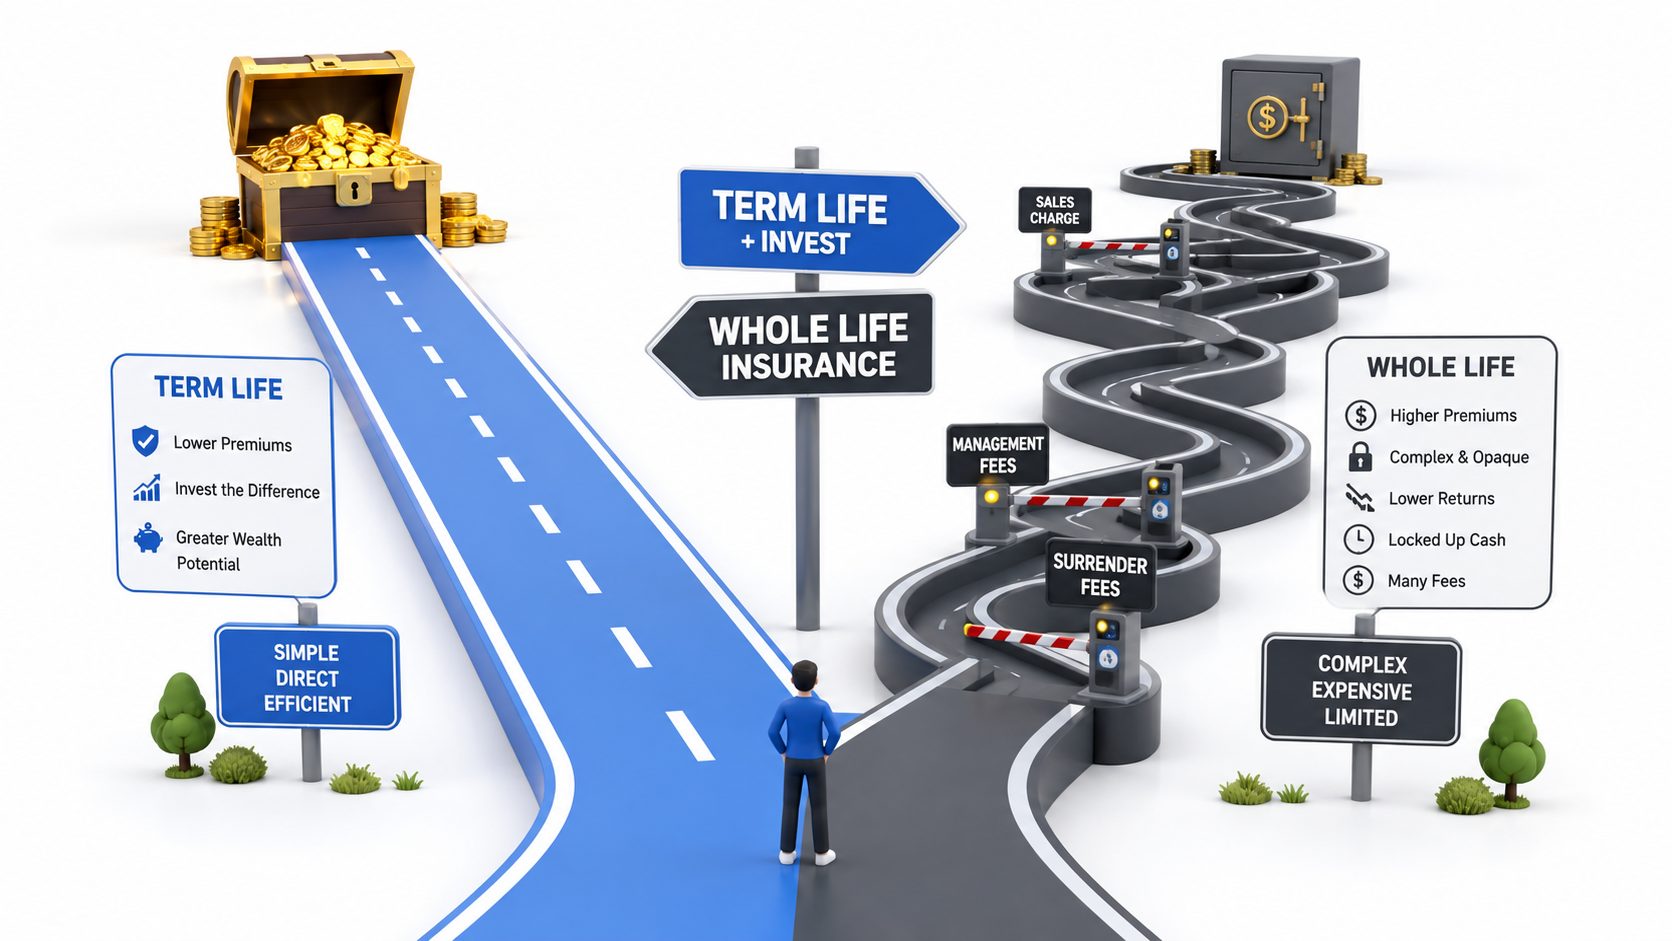
Term life is intended to provide coverage for a set period, often with a relatively lower initial premium and generally no usable cash value. Whole life is cash-value insurance with premiums typically paid on a schedule; it can support long-lasting coverage if payments and policy terms are met. The Idaho Department of Insurance distinguishes term cover for a set number of years from whole-life cover that can last for life; the cost comparison still needs actual quotes. The California Department of Insurance life guide describes the trade-offs between temporary term protection, permanent coverage, cash values and policy loans. Neither regulator says one product fits a fixed percentage of families.
The first calculation is the coverage gap: future income and obligations your household would lose, minus assets and dependable cover already available. Then choose a duration. A parent who needs protection until a mortgage is paid and children are independent may value a 20- or 30-year term. Someone who needs a death benefit irrespective of when death occurs may need to examine permanent cover. The reason for coverage should drive the product comparison, not a projected investment chart.
A matched-quote worksheet
Obtain written quotes for the same death benefit from insurers that can underwrite your health and circumstances. For term, record the end date, whether premiums stay level throughout the initial term, and what renewal or conversion would cost or permit. For whole life, obtain the required premium schedule, guaranteed cash values, any non-guaranteed dividends or illustrations, policy-loan terms, surrender charges and the death benefit at several future years. These are policy-specific values. A generic “whole life earns 3% after fees” claim cannot replace them.
| Checkpoint | Term quote | Whole-life illustration |
|---|---|---|
| Benefit | Amount while term remains in force | Amount while policy remains in force |
| Premium | Initial schedule and renewal terms | Scheduled payments and any flexibility |
| Policy end | Expiry, renewal and conversion provisions | Lapse and maturity provisions |
| Value while alive | Usually no cash value | Guaranteed and non-guaranteed cash or surrender values |
| Borrowing | Usually not available against policy value | Loan rate, loan balance and death-benefit effect |
The Texas Department of Insurance advises comparing policy types, premiums and projected values and reviewing what happens if you stop paying. Keep the written illustrations rather than relying on an agent’s verbal return estimate. When you compare a new policy with an old one, the California and Texas insurance guides warn that health changes can alter price or eligibility; do not cancel current coverage before replacement cover is effective.
A hypothetical premium comparison
Suppose two illustrative quotes, neither offered to a real reader, provide a $500,000 death benefit: a 20-year term at $50 per month and a whole-life policy at $200 per month. Over 20 years, ignoring premium changes, the term premiums sum to $12,000 and whole-life premiums sum to $48,000. The $36,000 difference is a potential amount to save or invest. It is not an insurer’s guaranteed profit, a universal premium ratio, or proof that one policy is better. The whole-life contract could still be in force after year 20; the term contract may end then. A proper comparison values that difference in coverage duration.
Hypothetical 20-year premium outlay
“Buy term and invest the difference” means buying enough term protection and actually investing the amount left from a chosen budget. If the household invests $150 at each month-end for 20 years, it contributes $36,000. Under fixed nominal return assumptions of 3%, 5% and 7% a year, compounded monthly with no taxes or fees, the final values are approximately $49,245, $61,655 and $78,139. These are mathematical scenarios, not forecasts or guaranteed market results. Real investments can decline; tax, fees, missed contributions and sequence of returns change the outcome.
Hypothetical $150 monthly investment over 20 years
Do not compare that hypothetical investment balance with an invented whole-life cash value. Ask the insurer for its guaranteed year-20 surrender value and any non-guaranteed projection under its own illustration. Then compare like-for-like cash available if you stop coverage at year 20. If the need extends beyond year 20, also price the term renewal or a new policy; age and health can make future coverage expensive or unavailable. The California insurance regulator explains that sales illustrations separate guaranteed from non-guaranteed future values.
Cash value, death benefit and policy loans
Whole-life cash value is not automatically paid on top of a stated death benefit. The way cash value and death benefit relate depends on the contract and any riders. A policy loan also is not a cost-free withdrawal: interest accrues, and an unpaid balance can reduce what beneficiaries receive. Read the policy’s loan and surrender terms, including possible tax consequences, before using cash value. The California regulator’s guide tells buyers to examine cash value, loans and the benefit actually payable.
Whole-life illustrations often show both guaranteed values and values that rely on future dividends or other assumptions. The latter are not promised returns. Some cash-value policies build little early surrender value; the Texas guide says to check what the policy will be worth if you need to stop paying. Conversely, a term policy’s low initial price may cease to be an advantage if you still need substantial cover after expiry and renewal is expensive. The relevant question is the total cost and benefit over your own coverage horizon.
Five questions before deciding
- Who would need the death benefit, how much, and for how many years? Include debts, education, care and income replacement instead of relying on a fixed multiple of salary.
- Are both quotes underwritten for the same person and benefit? A “ten times more expensive” comparison built from unrelated people or benefit amounts is meaningless.
- What is guaranteed? Mark guaranteed premiums, death benefits and surrender values separately from non-guaranteed illustrations and hypothetical investment returns.
- What happens if circumstances change? Check term renewal and conversion, whole-life surrender and loan provisions, and whether employer cover can be retained after leaving a job.
- Can the household keep the strategy? Term plus investment requires disciplined saving and tolerance for market risk. Whole life requires sustained premiums to keep the policy in force.
The Texas insurance regulator suggests reviewing coverage every few years and comparing old and new policies before replacing one. The California and Texas guides also provide practical buyer checklists. Bring the two quotes and their illustrations to an adviser who can explain the contract details and disclose how they are paid. That is more useful than accepting a universal ranking or a chart built on assumed insurer returns.