September 2026 is the application date, not the start of protection
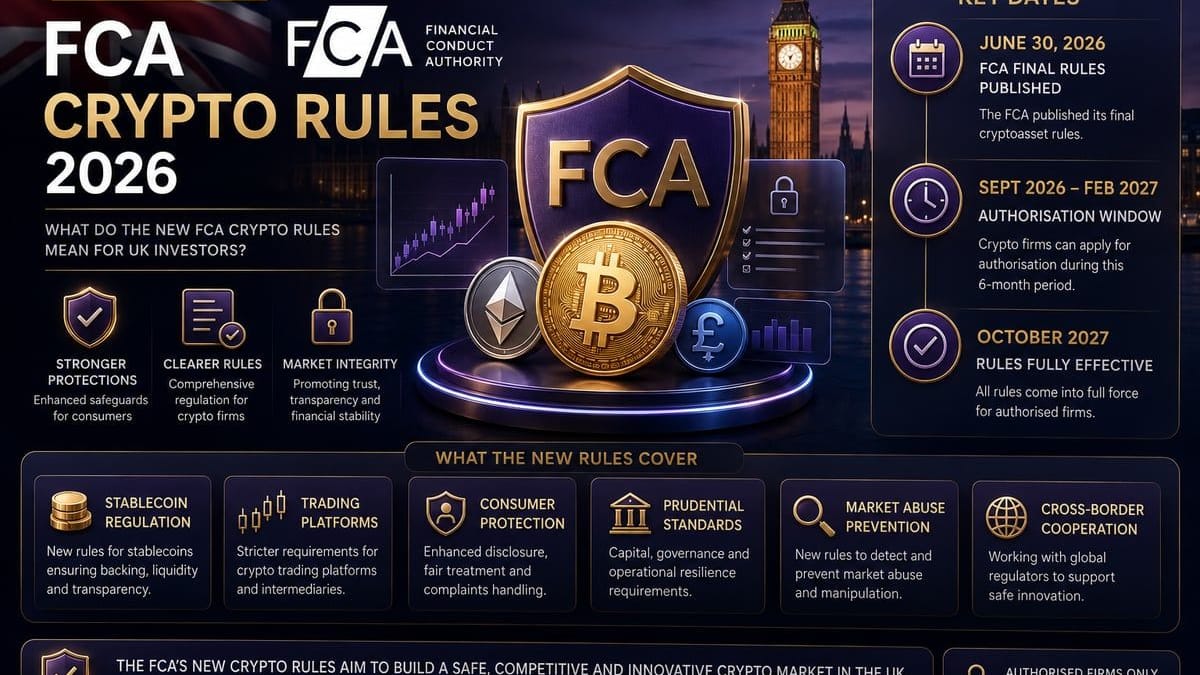
A UK crypto exchange may apply for the new FCA permission from 30 September 2026, but the broader cryptoasset regime is due to start on 25 October 2027. Those dates describe different events. The FCA’s application guidance gives the gateway window as 30 September 2026 to 28 February 2027 and says firms carrying out the newly regulated activities need permission for the 2027 start. A customer checking an exchange on 1 October 2026 should not treat a submitted application as a licence or as insurance for their holdings.
The FCA published a package of final cryptoasset rules on 30 June 2026 and perimeter guidance on 16 September. The rules provide a framework for future permissions. They do not make every crypto firm fully FSMA-authorised in September 2026. The old article on this page mixed the application date, the regime start, current promotion rules and unverified custody requirements. Those distinctions determine what a saver can actually check today.
Four checkpoints between now and October 2027
| Date | What happens | What it means for a customer |
|---|---|---|
| 30 June 2026 | FCA publishes final policy statements | Rules are available for firms to prepare; the future regime has not started. |
| 30 September 2026 | FSMA authorisation gateway opens | Firms may apply; a pending application is not approval. |
| 28 February 2027 | The stated application period closes | Transitional arrangements depend on the firm’s application and circumstances. |
| 25 October 2027 | New regime starts | In-scope business generally needs the relevant FCA permission or an applicable saving or transitional arrangement. |
Days after the 30 September 2026 application opening
The two deadlines after the gateway opens are 151 and 390 calendar days from 30 September 2026 respectively. They are planning intervals, not processing-time promises. The FCA says firms that apply during the window may continue under specified saving provisions if a decision is still pending at commencement; it does not promise every application will be approved. Its gateway explanation sets out those conditions. Pre-application meetings became requestable in May 2026 and were scheduled from July; they are preparation, not authorisation.
What the FCA supervises today
Some crypto exchanges and custodian-wallet providers already need registration under the Money Laundering Regulations (MLRs) to operate in the UK. FCA transition guidance says that obligation continues until the FSMA regime begins for firms within the present scope. It also states that MLR registration does not guarantee future FSMA authorisation. An FCA entry may therefore describe a narrow AML registration or a permission for another business, not a general guarantee that all of the firm’s crypto services are regulated.
The FCA also has financial-promotion rules for qualifying cryptoassets. In particular, its existing rules require at least a 24-hour cooling-off period before a new customer is shown certain direct-offer promotions. That rule was introduced before the 2027 authorisation regime. It is not a universal one-day freeze on every deposit, and it does not make a token safe. The FCA’s review of promotion compliance explains the scope of that cooling-off rule.
If a platform claims “FCA regulated,” ask which legal entity you contract with and what activity appears on the FCA register. Check the register entry and any warning directly, then read the custody and withdrawal terms. An approval to send a financial promotion, an AML registration and future FSMA permission are distinct.
Which activities will need the new permission?
The FCA’s September perimeter guidance names issuing qualifying stablecoins, operating a cryptoasset trading platform, dealing or arranging deals, safeguarding cryptoassets and arranging staking. The precise perimeter has legal definitions and exemptions. An app that merely discusses tokens is not automatically a regulated trading platform, and overseas services raise separate location questions. Firms need to assess their activity against the FCA guidance, rather than extrapolating from an article’s short list.
The FCA’s June policy package includes activity, prudential, stablecoin, admission and market-abuse rules. The previous version of this article claimed a universal 95% cold-storage rule, a precise 1% capital buffer on every significant stablecoin and prescribed monthly attestations. Those numbers were not supported by the cited FCA material and should not be used to judge whether your exchange is compliant. The relevant rulebook and the firm’s granted permission are the proper references once the regime starts.
Authorisation is also not FSCS insurance for a cryptoasset holding. The FCA warns that a person buying cryptoassets can lose all their money and does not have FSCS protection for those assets. The UK’s £120,000 FSCS deposit limit, effective since December 2025, covers eligible deposits at UK-authorised banks, building societies and credit unions, not coins in a wallet. The FSCS explains that deposit limit separately.
Tax reporting has its own calendar
The Cryptoasset Reporting Framework (CARF) is an HMRC reporting system, separate from FCA authorisation. Reporting service providers collect user and transaction information for 1 January through 31 December 2026 and submit the first report by 31 May 2027, according to HMRC guidance. An exchange’s CARF report is not a replacement for an individual checking their own tax return.
For a simple UK disposal in 2026–27, HMRC lists a £3,000 annual exempt amount and general individual Capital Gains Tax rates of 18% and 24% depending on the person’s other taxable income and gains. Suppose Leah has £10,000 of net chargeable crypto gains, no other gains or losses and her entire taxable gain remains in one tax band. After the £3,000 exemption, £7,000 remains. That would produce £1,260 at 18% or £1,680 at 24%. It is an illustration, not a claim that everyone pays one flat rate. Keep purchase records, disposal values, fees and transfers; HMRC’s current CGT guidance should control the actual calculation.
Leah’s illustrative tax on a £10,000 net crypto gain
Buying, selling, exchanging one token for another, and using crypto to pay can each have different tax consequences. The earlier “10% or 20%” claim on this page was stale for 2026–27. Staking receipts can involve income-tax questions as well; this guide does not assign one tax treatment to every staking arrangement.
A short check before you send money
First identify the legal entity and its present FCA registration or permission. Next, read exactly what service the entity will perform and where your assets will be held. Then check whether withdrawal rights, fees, risk warnings and customer-support arrangements match what the app advertised. Keep a record of any pending transfer. Do not infer FSCS protection from a logo, an FCA application, a crypto ETN listing or a bank account used to fund the purchase.
The immediate consumer rule is plain: the new cryptoasset permission is a 2027 event, while AML registration, promotion rules and tax obligations already operate. Even after authorisation begins, a token can lose value and direct holdings still lack FSCS protection.