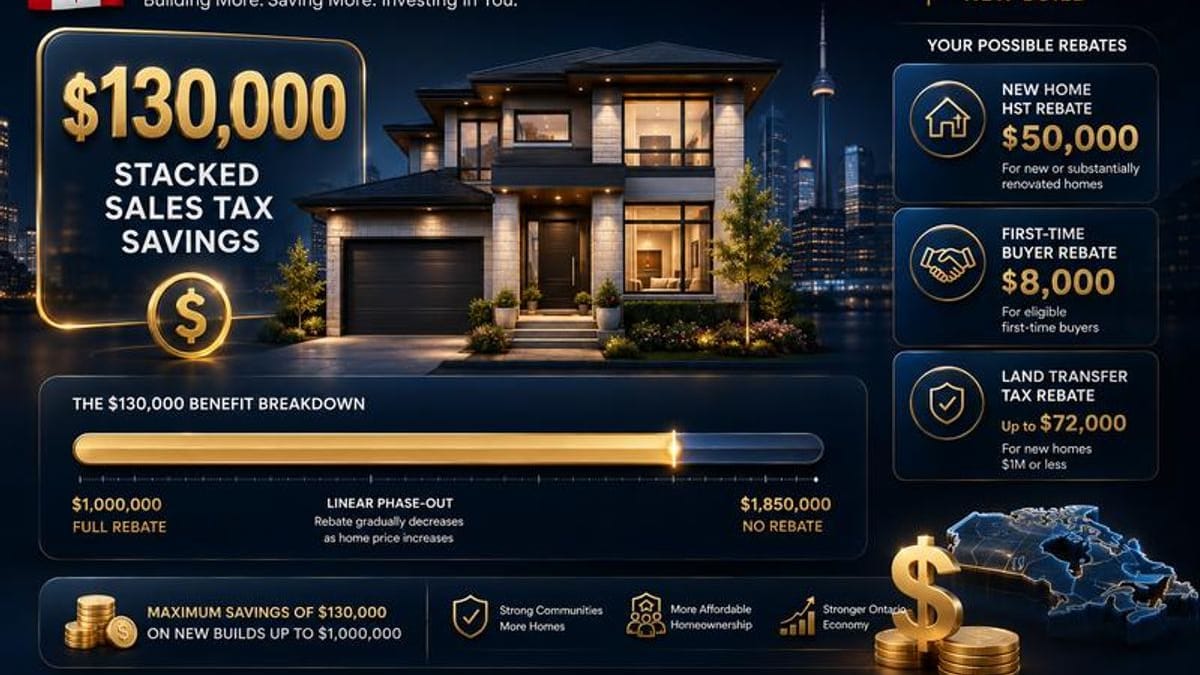
A repeat Ontario buyer can now reach C$130,000 in relief
A qualifying Ontario repeat buyer of a C$1 million new home can receive C$80,000 through the Ontario Enhanced New Housing Rebate (ENHR) and C$50,000 through the Ontario New Home Affordability Payment (ONHAP). First-time buyers may also reach C$130,000, but their federal rebate reduces ONHAP rather than creating another full 5% payment. That offset is the detail many rebate summaries miss.
Ontario's current ONHAP explanation, updated September 17, 2026, describes two provincial components. CRA administers ENHR on the 8% Ontario part of HST. Ontario administers ONHAP, a separate payment toward the federal 5% part. Federal housing rebates are deducted when Ontario sets ONHAP, so the same federal tax is never reimbursed twice. The buyer must qualify for ENHR before receiving ONHAP.
| Component | Who can qualify | Maximum during Ontario's window | What it covers |
|---|---|---|---|
| Federal first-time buyer GST/HST rebate | Eligible first-time buyers | C$50,000 | Up to the 5% federal HST on a new home |
| Ontario ENHR | Eligible Ontario owner-occupiers, including repeat buyers | C$80,000 | Up to the 8% Ontario HST |
| Ontario ONHAP | Buyers entitled to ENHR or its rental counterpart | C$50,000 before federal offset | Federal HST still unrecovered after federal housing rebates |
The temporary Ontario ENHR window generally covers agreements signed from April 1, 2026 through March 31, 2027. The federal first-time buyer window has separate dates: qualifying builder agreements are generally signed on or after March 20, 2025 and before 2031, with construction and completion rules. The price calculator assumes those conditions and intended primary-residence use are met; a price alone cannot confirm eligibility.
How the federal rebate changes Ontario's payment
The federal first-time buyer rebate covers the full 5% GST/HST federal slice on an eligible home priced up to C$1 million, with a C$50,000 cap. Between C$1 million and C$1.5 million, it phases to zero. A standard, smaller federal new-housing rebate can still apply to certain qualifying non-first-time purchases below C$450,000. Ontario subtracts whichever federal housing rebate a buyer is entitled to claim from the gross ONHAP amount.
For a home priced at C$1 million or less, potential gross ONHAP is the 5% federal part of HST. From C$1 million through C$1.5 million, it holds at C$50,000. It then tapers until C$1.85 million, where it ends. The actual payment is the gross Ontario amount less the federal portion already available, floored at zero. Ontario Regulation 196/26 gives the legal formulas; Ontario's own page gives the price bands and offset.
Consider two C$850,000 purchases. First-time buyer Aisha can receive C$42,500 from the federal program and C$68,000 ENHR. Her ONHAP is zero because the federal rebate has returned the full 5% slice. Repeat buyer Renée does not get the first-time rebate at that price. If she qualifies for Ontario's temporary program and no standard federal rebate applies, she can receive C$68,000 ENHR and C$42,500 ONHAP. Both illustrative totals are C$110,500, equal to 13% of C$850,000. The payment route differs.
Renée's C$850,000 repeat-buyer relief
The chart shows Renée's Ontario components. It does not imply every repeat buyer will receive them: agreement date, property, tax paid, intended use and CRA assessment still matter. For a lower-priced repeat purchase, a standard federal rebate may reduce the ONHAP cheque while leaving the total federal-slice relief the same.
What happens above C$1 million
The first-time federal rebate shrinks after C$1 million, but Ontario's temporary top-up fills the gap for a qualifying Ontario purchase. At C$1.2 million, the federal first-time rebate is C$30,000. ENHR remains C$80,000. Ontario's gross ONHAP is C$50,000, reduced by C$30,000 of federal relief, so ONHAP pays C$20,000. The combined relief is C$130,000 and the remaining HST on a C$1.2 million before-tax price is C$26,000.
At C$1.45 million, the federal rebate is C$5,000, ENHR remains C$80,000 and ONHAP fills C$45,000. The total stays C$130,000. At C$1.5 million, the federal first-time rebate reaches zero; the Ontario components are C$80,000 and C$50,000. The difference among these three purchases is how much the federal government pays directly, rather than a sudden loss of combined relief at C$1.5 million.
Combined relief by new-home price for a qualifying Ontario first-time buyer
The enhanced Ontario amounts begin to taper above C$1.5 million. At C$1.6 million, ENHR is C$64,000 and gross ONHAP is approximately C$35,714. Federal first-time relief is zero, leaving around C$99,714 combined. At C$1.85 million the enhanced amounts end; an eligible buyer may still receive the standard Ontario new-housing rebate of up to C$24,000. The previous claim that all relief vanishes at C$1.85 million is wrong.
On a C$1.2 million home, HST before relief is C$156,000. ENHR covers C$80,000, the federal first-time rebate covers C$30,000 and ONHAP covers C$20,000. That leaves C$26,000 of HST. A builder's advertised HST-included price should be read against its rebate-assignment clause, because the contract may assume these claims are credited to the builder.
Who covers the HST on Aisha's C$1.2 million home?
The Home Buyers' Plan funds a deposit
A qualifying Home Buyers' Plan (HBP) withdrawal can move money from an RRSP into a down payment without an immediate taxable RRSP withdrawal. The CRA's current HBP page lists a C$60,000 per-person withdrawal limit. HBP money is the buyer's own retirement savings and is subject to repayment rules. It does not add another C$60,000 of tax relief to ENHR, ONHAP or the federal housing rebate.
Aisha might withdraw C$60,000 from her RRSP and receive C$130,000 housing-tax relief on her C$1.2 million purchase. The C$60,000 helps fund closing; the C$130,000 reduces HST if the purchase qualifies. Calling C$190,000 a rebate would mix an RRSP withdrawal with a genuine tax refund. The site's new-home relief calculator reports the HST relief total separately from an illustrative HBP tax deferral.
An RRSP contribution may generate a deduction under ordinary RRSP rules, but that deduction is not created by the HBP withdrawal. A future unpaid HBP repayment can be included in income. Work out down-payment cash flow and tax relief as separate steps before deciding how much RRSP money to use.
Who receives ONHAP and when
Ontario says ONHAP depends on an ENHR or Enhanced New Residential Rental Property Rebate (ENRRPR) entitlement. CRA administers the qualifying underlying rebate. With the applicant's consent, CRA shares the information needed for Ontario to determine its separate payment. If the builder paid or credited the relief to the buyer, the builder submits the rebate application. Otherwise the buyer applies. The CRA's ENHR notice and Ontario's ONHAP page should be read together.
That sequence matters for closing costs. A program may ultimately reimburse tax while the closing statement still requires you to pay it first. Ask the builder which rebate it is crediting, who submits each form, and who bears the cost if CRA later finds the conditions were not met. Do not treat the full calculated amount as cash in the bank on the signing date.
The owner-occupied route requires the home to be bought or built for use as a primary residence and has first-occupancy conditions. A property acquired for rental use follows different rebate rules. Current CRA owner-occupier guidance does not state a universal 12-month continuous-occupancy rule that automatically claws back every rebate after an earlier sale or lease. The facts and eligibility path matter. If your plans change, examine the rental-property rules and obtain case-specific advice before representing the purchase as owner-occupied.
A practical check before you sign
First, record the before-tax home price and the builder agreement date. Check whether the federal first-time buyer window applies, then check Ontario's temporary ENHR window. Next, confirm whether each person on title meets the federal first-time buyer definition; the CRA also considers a spouse or common-law partner's owned primary residence during the current and previous four calendar years. Do not assume a parent's status is harmless merely because they are helping with financing.
List the amounts in three columns: federal housing rebate, Ontario ENHR and net ONHAP after the federal offset. Compare their sum with the HST actually charged. If the builder says the advertised price includes rebates, ask for the assignment and closing-credit terms in writing. Keep the purchase agreement, tax invoices, occupancy evidence and CRA/Ontario correspondence. The estimate is useful when it helps you find a discrepancy before closing.
Ontario's temporary payment can fill the federal part left after a federal rebate, including for a repeat buyer, but it cannot pay the same federal tax twice. The province's September guidance is the current source for that rule; revisit it before filing because housing-rebate administration can change.