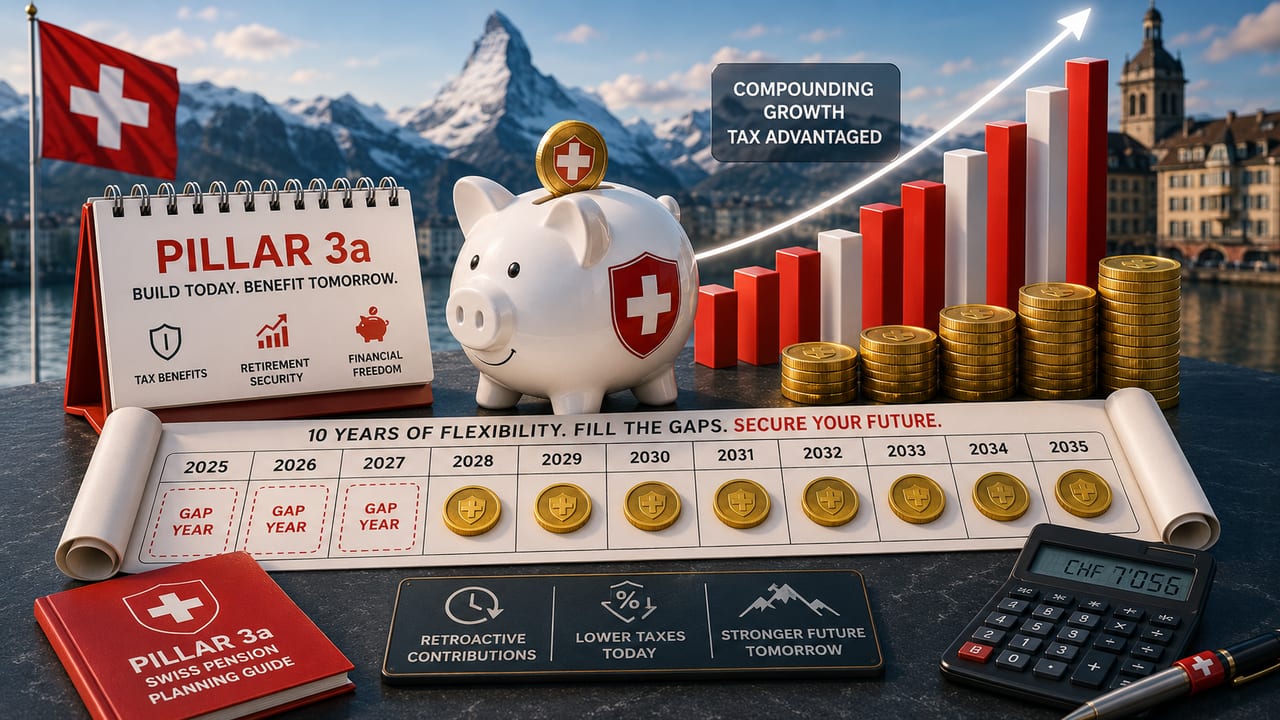
A Pillar 3a “buyback” is a payment in a current year to close an eligible missed Pillar 3a contribution gap from 2025 or later. It differs from the ordinary current-year payment, but both may be deductible in the payment year if the statutory conditions hold. The first buyback year is 2026, so this is a new planning option rather than permission to repair all historical missed years.
One annual ceiling across old gaps
The Federal Tax Administration's Circular 18a says the catch-up amount in a single tax year cannot exceed the small contribution limit—CHF 7,258 for 2026—even if several older gap years are combined. You must also pay your full permitted current-year ordinary 3a contribution before making a buyback.
Nora's 2026 application
Nora had AHV-liable income in 2025 but did not contribute to Pillar 3a. In 2026 she remains eligible, pays CHF 7,258 ordinary contribution, then arranges a CHF 7,258 buyback for her 2025 gap through her provider. She can potentially deduct CHF 14,516 total from 2026 taxable income. At a purely illustrative 25% marginal rate, the gross tax effect would be CHF 3,629, but the actual rate and use of deduction vary.
Documentation and other pension purchases
Nora should retain proof of 2025 eligibility, the prior contribution record and the provider's buyback certificate. A specific past year's gap can only be closed through one buyback; it cannot be split across years. Pillar 2 pension-fund purchases have a separate individually assessed ceiling and tax rules. They may coexist with 3a but cannot be portrayed as a standard CHF 25,000 available to everyone. BSV's overview gives the ordinary contribution and catch-up starting rules.