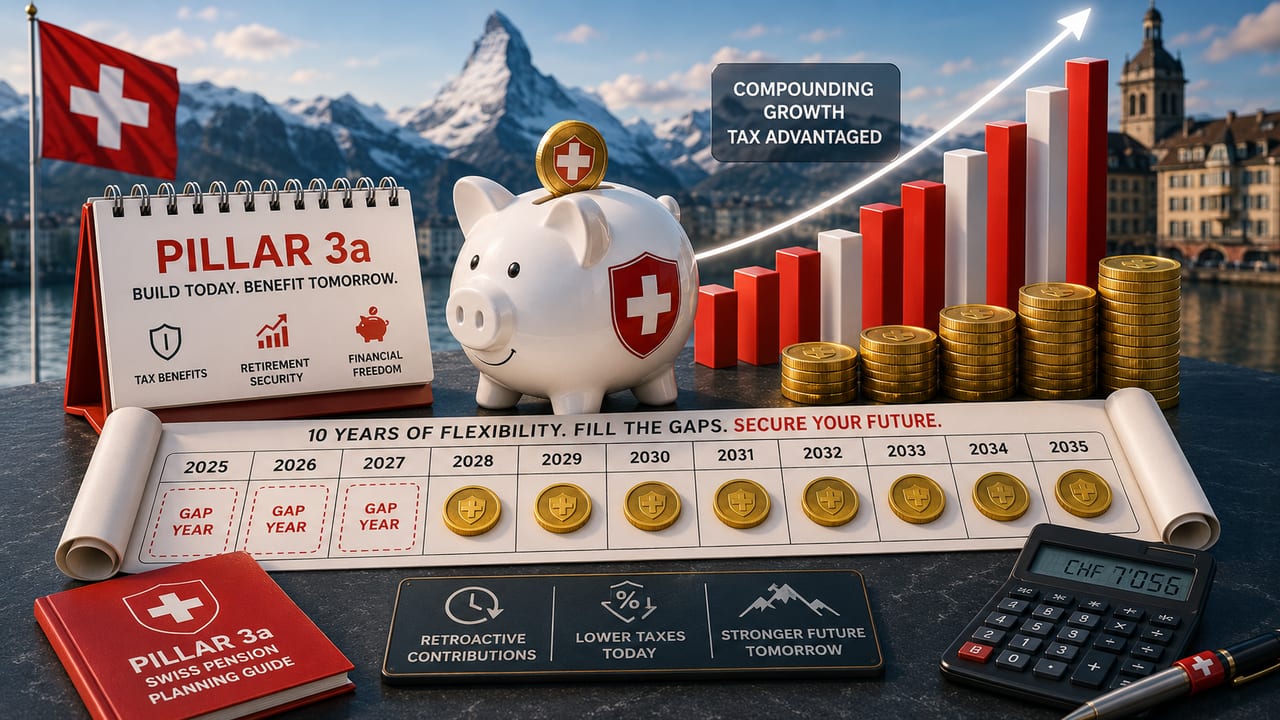
Switzerland first allowed Pillar 3a catch-up contributions in tax year 2026 for eligible missed 2025 contributions. The look-back can eventually reach ten years, but gaps before 2025 cannot be filled. To buy back a gap, the person must have been eligible to contribute in the gap year, still be eligible in the buyback year and first pay the full current-year permitted ordinary contribution. The Federal Social Insurance Office guide explains the start date and conditions.
The annual catch-up ceiling
The total retroactive buyback in one tax year is capped at the small Pillar 3a limit, CHF 7,258 in 2026, even if it covers several gap years. The Federal Tax Administration circular expressly allows several old gaps to be aggregated but caps the total annual buyback. A given year's gap can be filled by only one buyback, so plan which gaps to address first.
Marco's 2026 example
Marco, an employee with a Swiss Pillar 2 fund, missed all of his eligible 2025 small-limit contribution. In 2026 he first contributes his full ordinary CHF 7,258. He can then buy back up to CHF 7,258 for 2025, if all conditions are met. That gives CHF 14,516 of 2026 Pillar 3a contributions potentially deductible in 2026—not CHF 21,774 for two old gaps plus the current year. At an assumed 32% marginal tax rate, a fully usable CHF 14,516 deduction corresponds to about CHF 4,645 of tax reduction; the actual combined cantonal/federal rate varies.
Avoid borrowing against a hypothetical tax saving
The payment is retirement money subject to 3a withdrawal rules, not a cash rebate. If Marco has no AHV-liable earned income in a gap year, he may lack an eligible gap. If he already drew old-age Pillar 3a benefits, buyback eligibility can fail. A separate Pillar 2 buy-in can exist but depends on the pension fund's certified purchase room; it does not lift the 3a catch-up ceiling.