A Pensionskassen-Einkauf is a voluntary purchase into a Swiss occupational pension fund (Pillar 2) to fill certified room under the fund's rules. Unlike the flat small Pillar 3a annual contribution limit, Pillar 2 purchase capacity depends on the individual's salary, age, prior pension assets, plan benefits and any outstanding home-ownership withdrawal. A fund statement or confirmation must determine the actual maximum; a published CHF 20,000/50,000/200,000 range is not a universal entitlement.
Sophie's documented scenario
Assume Sophie's fund certifies CHF 85,000 of remaining purchase room and she chooses to pay CHF 30,000 in 2026, CHF 30,000 in 2027 and CHF 25,000 in 2028. Those amounts sum to CHF 85,000. If her actual effective marginal tax reduction happened to be a constant 34% in each year, the arithmetic would be CHF 10,200 + CHF 10,200 + CHF 8,500 = CHF 28,900. This is an illustrative rate assumption, not a Zurich tax-authority quote; real tax rates vary across years, income, municipality and deductions.
The three-year capital-withdrawal consequence
Under Swiss occupational-pension rules, a lump-sum withdrawal within three years after a purchase can jeopardise or reverse the tax deduction. This matters when retirement, home purchase or moving abroad is near. Review the Federal Social Insurance Office occupational-pension guidance and the official three-year tax-rule discussion with the fund and tax office. The earlier wording “you cannot withdraw capital” was too absolute for a tax-sensitive eligibility rule.
Compare with Pillar 3a correctly
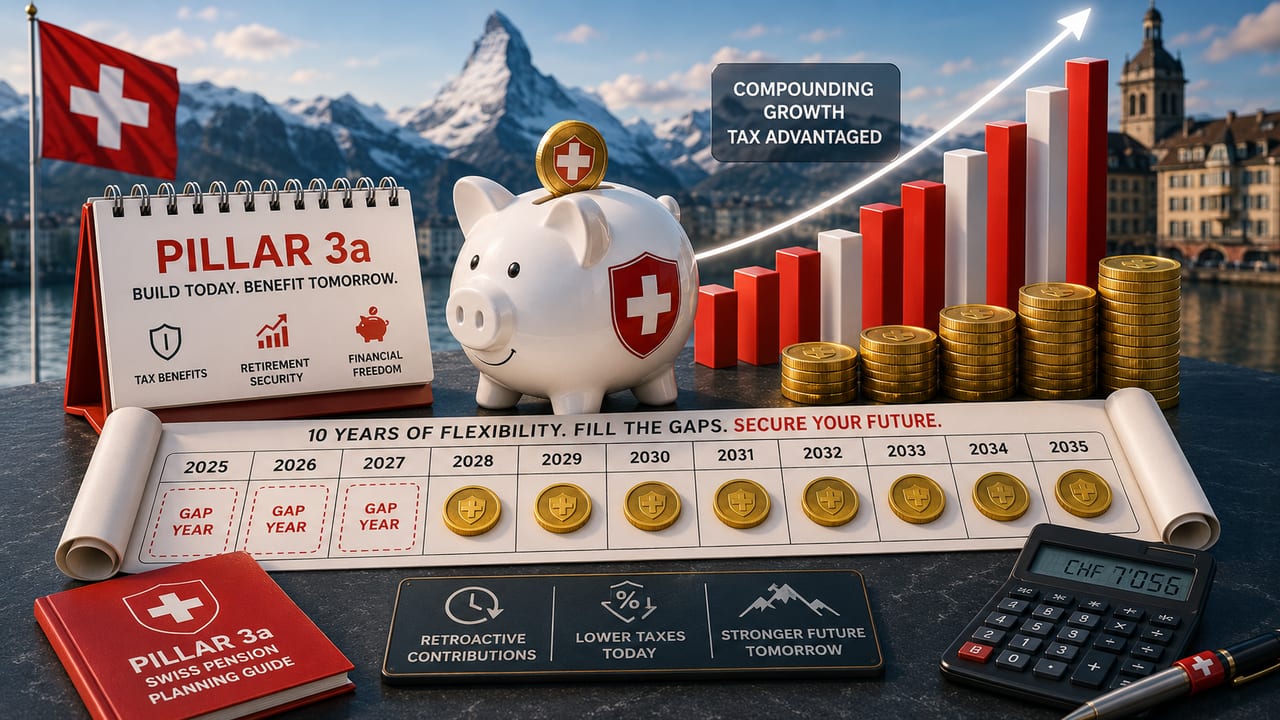
An eligible employed person with a Pillar 2 fund can contribute up to CHF 7,258 ordinary Pillar 3a in 2026 and, if conditions hold, up to another CHF 7,258 as retroactive 3a buyback for a missed 2025 gap. Those are separate from a certified Pillar 2 buy-in, but the 3a buyback cannot exceed its annual small-limit ceiling. The accompanying chart shows Sophie's assumed tax effect only; it does not forecast pension returns or say spreading always beats one payment.