Calculator
KVdR 9/10 Rule Eligibility Calculator
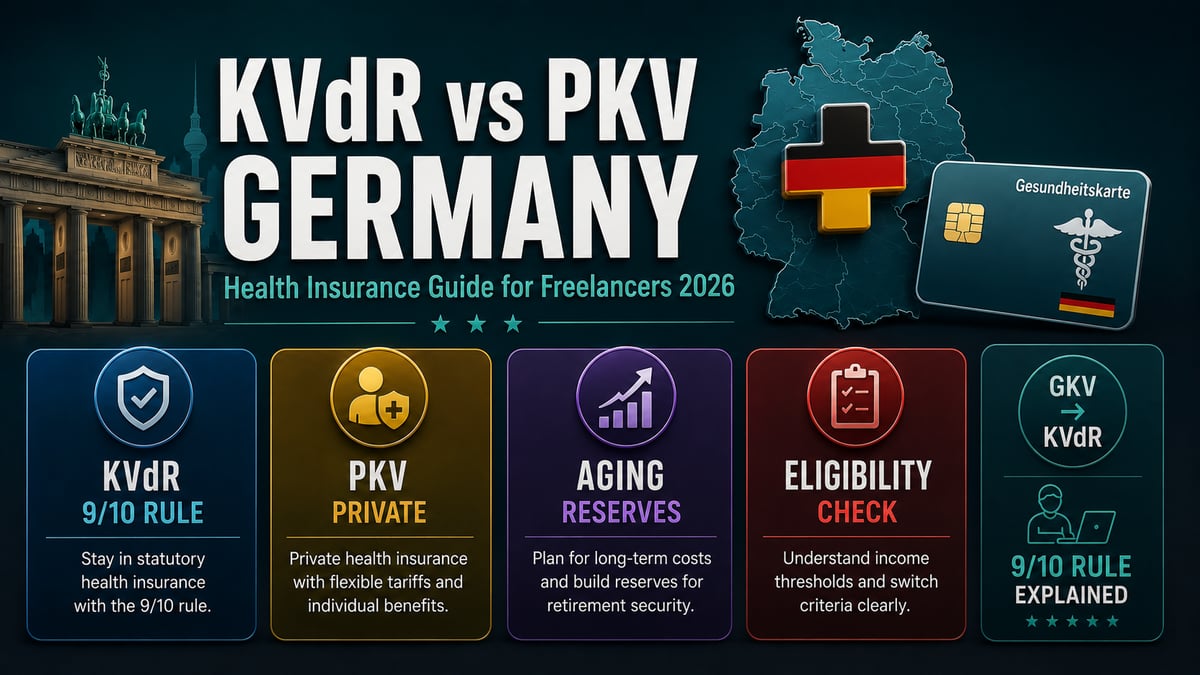
Calculate your Krankenversicherung der Rentner (KVdR) eligibility. Model GKV vs PKV years, check the 9/10 rule, and apply children's credits.
Try it nowAt €1,500 statutory pension and €800 monthly rent, illustrative 2026 net health costs are about €131 with KVdR, €266 with voluntary GKV, or €319 for a €450 private health premium after subsidy. Check the 9/10 rule first.
Adjust the variables below to simulate outcomes, compare rates, and see real-time projections.
A direct comparison of features, rules, limits, and eligibility requirements.
| Feature / Detail | GKV route (KVdR if eligible) | Private health insurance (PKV) |
|---|---|---|
First test | KVdR requires GKV periods in at least nine tenths of the second half of working life; three years are credited for each child. Otherwise voluntary GKV may be possible. | PKV eligibility and premiums depend on the person's employment status, age, health and actual tariff; a current private contract can continue in retirement. |
Contribution income in the model | KVdR member: statutory pension; voluntary GKV member: statutory pension plus rent and capital income. Occupational pensions and work income are outside this input set. | Private health premium follows the contract, not current pension or rent; the actual tariff can change later. |
2026 health rates | Statutory pension: 14.6% general rate plus a fund-specific additional rate, split with DRV. Rent/capital in voluntary GKV generally use the 14.0% reduced base plus the fund's additional rate. | No uniform PKV percentage. The user enters an actual monthly private health premium. |
Pension-insurance contribution | DRV pays half the GKV health contribution on statutory pension, automatically for compulsory KVdR or as a requested subsidy for voluntary GKV. | A private retiree may apply for a health subsidy based on statutory pension, capped at half the eligible actual private health premium. |
2026 assessment limits | GKV monthly income ceiling €5,812.50. A voluntary member also faces a minimum assessment base of €1,318.33 even with low income. | A private premium is contract-based; the GKV assessment ceiling does not cap it. |
Family coverage | Eligible spouse or children may qualify for GKV family insurance without an additional contribution, subject to income and other rules. | Each privately insured family member needs their own health cover; the exact family premium depends on each contract. |
Care and tariff benefits | GKV care-insurance contributions and medical co-payments are separate from the health-only numbers shown here. | Private long-term-care cover and room, specialist or deductible benefits depend on the purchased tariff and are not included here. |
Analyze the advantages and drawbacks of each financial product before making a decision.
Stefan expects €1,500 a month from the German statutory pension and €800 rent from a flat. The Federal Health Ministry's 2026 contribution page gives a 14.6% general GKV health rate, a 14.0% reduced rate for some other income, a 2.9% average additional rate and a €5,812.50 monthly assessment ceiling. Each health fund sets its actual additional rate, so the example substitutes the national average. The model is about health insurance only. Pflegeversicherung is a separate cost in both GKV and PKV and must be added from the reader's own information.
If Stefan meets the KVdR pre-insurance test and has no occupational pension or assessable work income, the €800 rent does not raise this compulsory GKV health contribution. Half of 17.5% on his €1,500 statutory pension is €131.25 monthly after the pension insurer's share. If he instead has voluntary GKV, the pension's gross health contribution is €262.50, the €800 rent contributes €135.20 at 16.9%, and the DRV health subsidy on the statutory pension is €131.25. The net is €266.45. These different figures reflect different contribution bases, not different treatment of the same rent inside KVdR.
Suppose Stefan also has a real €450 monthly private health-insurance premium. The pension-linked health subsidy is €131.25 at the example's 2026 average rate and below the separate half-premium ceiling of €225. His net private health premium would be €318.75. The number does not include his private care cover, tariff deductible or a spouse's policy. Calling €450 his net cost while calling €131 the KVdR cost would overstate the private route. A homeowner with an occupational pension should not put that amount in the rent field; DRV's pensioner guide explains why that income can trigger a different GKV charge.
KVdR membership is a documented insurance-history test. For an illustrative 40-year working life, its second half is 20 years and nine tenths of that is 18 years. Stefan enters 13 actual GKV years in that half and one child credit worth three years: 16 credited years, two short. The widget therefore prices voluntary GKV against his actual private quote. It does not display a €0 or €131 KVdR option and pretend Stefan can choose it. If his record instead contains 15 actual GKV years plus the same child credit, it reaches 18 and the KVdR health calculation applies. The pension fund and health insurer, not a slider, determine the real legal count.
The counted years can include compulsory, voluntary and qualifying family GKV membership. Periods outside Germany and European coordination cases need individual checking, and the start and end dates matter more than rounded calendar years. The three-year credit per child is a pre-insurance rule; it is not three years of pension contributions and does not promise that every other family member is insured for free. Deutsche Rentenversicherung's KVdR material is the source for the career-half test and the contribution differences. Ask the health fund to confirm the insurance history before relying on a price comparison.
A person who misses KVdR may remain in voluntary GKV, depending on the insurance biography, or may have private cover. Voluntary GKV has a broader income base. BMG's 2026 minimum assessment base is €1,318.33 monthly, so a zero in the rent field does not promise a zero health bill to someone with little pension income. The live calculation uses this floor. It also caps assessable income at €5,812.50 a month, then subtracts the pension insurer's share where applicable. Actual long-term-care contributions, medical co-payments and any minimums tied to the individual's situation still need a separate statement.
A PKV policy is a contract with specified medical benefits, a deductible and a premium. Private hospital rooms or shorter appointment waits are not guaranteed by the letters PKV; they depend on the purchased tariff and provider. The €450 input is Stefan's hypothetical current health quote, not a German average. No regulator has set a universal 3% to 5% annual PKV rise, so this page no longer compounds that figure into a guaranteed age-85 cost. Get the insurer's renewal terms and test a range of possible future premiums in your own budget.
DRV's current subsidy guidance says a privately insured pensioner can request a health subsidy based on statutory pension, but it cannot exceed half the eligible private health premium. For a €100 monthly health tariff, even a very high statutory pension cannot produce a subsidy above €50 and make the policy free. The widget enforces that cap. There is no corresponding DRV subsidy for private long-term-care cover. For voluntary GKV, the subsidy follows half the health contribution attributable to statutory pension; rent is not subsidized.
Switching between PKV and GKV late in life is governed by more than one headline age. SGB V section 6(3a) can block compulsory GKV after 55 when the person was outside GKV for the preceding five years and meets further conditions. It is not a blanket rule that every person above 55 is legally forbidden to join. A household comparing cover should check age, prior insurance, family status and employment history with the health insurer before assuming a route exists. If private cover is available, put the premium, deductible, spouse's cover and care insurance on one page; compare the same benefits instead of a health-only premium with a full GKV bill.
Stefan's illustrative €1,500 statutory pension and €800 monthly rent produce about €131 monthly KVdR health cost at BMG's 2026 average additional rate. If he misses the 9/10 pre-insurance test, voluntary GKV is about €266 net of the pension-insurance subsidy because his pension and rent both enter the model at their applicable health rates. A €450 actual private health quote becomes about €319 after its subsidy, capped at half the premium. These are health-only comparisons: occupational pensions, work income, long-term-care premiums, tariff deductibles and future rate changes are not modelled. His entered 40-year career, 13 GKV years in the second half and one child yield 16 credited years against 18 required, so the live widget correctly shows voluntary GKV, not a fictional €131 KVdR choice. The figures are not a universal ranking; obtain the insurer's eligibility determination and real premium quote before choosing.
A retiree whose health fund confirms KVdR eligibility, or who has priced voluntary GKV using all assessable income and values its actual coverage and family rules.
A retiree with a real PKV health quote, a checked DRV subsidy and separately budgeted private care cover whose tariff fits the household's needs.
These links include relevant regulators and page-specific references. Worked examples and projections may also use stated assumptions: